Florida boards looking to refinance HOA loan debt usually have a specific problem to solve. The current loan may be approaching maturity, the association may need additional money for repairs or several financial obligations may have become difficult to manage separately.
This guide explains how refinancing works for Florida condominium associations, homeowners associations and co-ops. It covers what to review in the existing loan, how to compare a replacement loan, when consolidation can make sense and what the board should prepare before making a decision.
What refinancing an association loan actually changes
Refinancing means replacing an existing association loan with new financing. At closing, the new financing generally pays off the outstanding balance owed to the current lender. The association then repays the new obligation according to its new loan documents.
For an association, refinancing may have several purposes. A board might want to address an approaching maturity date, restructure payments, finance additional capital work or combine the existing balance with new project funding.
That distinction matters because the board shouldn’t evaluate a refinance based only on whether the new monthly payment looks lower.
A longer repayment period can reduce the current payment while increasing the amount of interest paid over the life of the obligation. A lower interest rate may improve the economics, but only after the board considers closing costs, any payoff charge on the current loan and other terms of the replacement financing.
The association also needs to understand whether it is simply replacing existing debt or increasing its total borrowing.
| Financing approach | What happens | What the board should compare |
| Straight refinance | A new loan pays off the existing association loan | Payoff amount, new rate, term, amortization, fees and total debt service |
| Refinance with additional funding | Existing debt is paid off and new money is added for a project | All refinance costs plus the complete project budget and resulting assessment obligation |
| Debt consolidation | Multiple eligible association obligations are combined into one financing structure | Total payoff amounts, which debts can be included, new payment and overall cost |
| Keep the current loan | The association leaves existing financing in place | Remaining term, balloon risk, rate, covenants and the cost of funding new needs separately |
TuCielo’s association financing program specifically includes the ability to refinance an existing HOA loan and, subject to underwriting and final terms, combine that balance with financing for additional project scope.
Refinancing therefore doesn’t have to be treated as a stand-alone transaction. For an association facing both old debt and a new repair requirement, the board can evaluate the full capital plan together.
When should a board refinance HOA loan debt?
A refinance is worth evaluating when the existing financing no longer matches the association’s current financial or property needs. That doesn’t mean refinancing will always produce a better outcome.
Boards should start with the problem they want the new financing to solve.
The current loan is approaching maturity
Some association loans have an amortization schedule that extends beyond the contractual maturity date. For example, payments could be calculated over a longer amortization period while the loan itself matures sooner.
That structure can leave a remaining balance due at maturity, commonly referred to as a balloon payment. If the association doesn’t have enough cash available, it may need to refinance, levy an assessment or use another permitted funding source.
Waiting until the maturity date is close can reduce the board’s room to compare alternatives. The loan documents should tell the board exactly when the debt matures and how the payoff amount is calculated.
The association needs more money for newly identified repairs
The original loan may have funded one project while a later inspection, engineering report or contractor scope identifies additional work.
For example, an association might already have financing for roofing but later determine that concrete restoration, waterproofing or elevator work also needs funding. Taking a second loan is one possibility, but it can result in separate payments, separate lender requirements and overlapping financial covenants.
A refinance that pays off the first loan and finances the additional work can be easier to evaluate as one overall obligation.
The current payment is putting pressure on the budget
A board may consider refinancing when the current debt service is difficult to support alongside insurance, reserve contributions, operating expenses and other assessments.
The board should still look beyond the monthly payment. Extending repayment can lower near-term debt service while increasing the length and potentially the total cost of the financing.
The relevant comparison is the complete cash flow impact over time.
Several obligations are competing for the same assessment revenue
An association may have an existing loan plus active project obligations or other eligible debt. In this situation, the board may want to consolidate HOA debt rather than managing several separate financing arrangements.
Consolidation can simplify the payment structure, but combining obligations doesn’t make the underlying debt disappear. The board needs a payoff statement for each obligation and should compare the combined balance with the proposed replacement financing.
The existing lender won’t increase the loan
Some lenders may be willing to finance the original project but unwilling to add a second phase or substantially increase the outstanding balance.
That doesn’t automatically mean the association has no financing path. Different lenders use different underwriting standards. Boards can compare a new lender’s proposal against the cost and restrictions of keeping the existing loan and funding the new work separately.
TuCielo states that its association financing can refinance a current balance and roll qualified additional scope into the new financing.
What should the board review before replacing the existing loan?
Before requesting proposals, the board needs a clear picture of what it already owes.
Starting with the existing loan documents also helps prevent a common mistake: comparing the proposed new principal amount with the original loan amount rather than the actual amount required to exit the current financing.
Request the current payoff amount
The outstanding principal shown on a financial statement isn’t always the same amount required to pay off a loan on a particular date.
Ask the current lender for a payoff statement or the process for obtaining one. Review whether the amount includes accrued interest, administrative costs, prepayment charges or other amounts required under the loan agreement.
The board should also confirm how long the payoff quote remains valid.
Check for prepayment provisions
Some loan agreements allow early repayment without a charge. Others can include prepayment conditions or costs.
These provisions directly affect refinance economics.
Suppose a new lender offers more favorable terms but exiting the existing loan requires a significant payment. The board needs to include that amount in its comparison rather than treating the new interest rate as the only measure of savings.
Compare the term and amortization separately
The term tells the board when the loan matures. Amortization describes the schedule used to calculate principal and interest payments.
They can be different.
A board reviewing a refinance should ask whether the replacement financing will be fully paid by maturity or whether a balance could remain. This is especially important when refinancing is being used to solve an existing balloon payment problem.
Review lender covenants and security
Association loan agreements can contain requirements that continue long after closing.
Depending on the financing, the association may be required to maintain insurance, follow collection procedures, provide financial reports, maintain accounts or reserves, meet financial conditions or obtain consent before taking on additional debt.
This is why boards should review the entire agreement with association counsel rather than comparing only a term sheet.
Associations preparing for underwriting can use TuCielo’s overview of Florida HOA loan requirements to organize financial records, governing documents, insurance information and project documentation before approaching a lender.
Confirm authority and required approvals
Refinancing is an association obligation, so the board needs to confirm that it has followed the approval process that applies to the community.
For Florida condominiums, the declaration, articles and bylaws need to be reviewed alongside Chapter 718 of the Florida Statutes. Florida law includes specific borrowing provisions in certain situations, including emergency powers, while other borrowing decisions can depend on the association’s governing documents and the purpose of the financing.
Homeowners associations should similarly review their governing documents together with Chapter 720 of the Florida Statutes.
Because approval requirements depend on the association, governing documents and transaction structure, boards should have Florida association counsel review the proposed action before signing financing documents.
Account for reserve and SIRS obligations
Refinancing existing debt doesn’t remove a condominium association’s separate reserve responsibilities.
This is particularly relevant for associations subject to a Structural Integrity Reserve Study (SIRS). The Florida Department of Business and Professional Regulation describes a SIRS as a reserve planning study addressing major structural components and the funding needed for anticipated repair or replacement.
Current Florida law allows qualifying condominium associations to use regular assessments, special assessments, lines of credit or loans to fund specified structural reserve obligations. Certain loan or line-of-credit approaches require approval by a majority of the total voting interests and must satisfy statutory requirements.
Boards dealing with SIRS-related expenses should therefore coordinate the refinancing plan with the association’s current reserve study, budget and legal requirements. The state’s condominium inspection and SIRS guidance provides current information about these obligations.
This article provides general educational information. Association boards should obtain legal, accounting and financial advice appropriate to their own documents and circumstances before approving debt.
A step-by-step process for refinancing an association loan
A board can make the refinance process easier to evaluate by treating it as a structured review rather than immediately requesting a new loan amount.
1. Define why the association is refinancing
Write down the financial problem before discussing loan structures.
Is the goal to:
- Pay off a loan approaching maturity?
- Reduce current debt service?
- Replace an unfavorable structure?
- Add funding for a newly identified project?
- Combine existing financing with additional project costs?
- Consolidate several eligible obligations?
A proposal can’t be judged properly until the board agrees on what success means.
2. Build a complete picture of current debt
Create a schedule showing every outstanding association obligation relevant to the transaction.
For each one, record the lender or creditor, outstanding balance, maturity date, current payment, interest structure, prepayment terms and security or covenants.
If the association intends to consolidate debt, obtain current payoff information rather than relying solely on accounting balances.
3. Update the association’s financial information
A refinance application is also a new underwriting event.
Lenders may need recent financial statements, the annual budget, bank statements, delinquency information, reserve information, insurance records and existing debt documents. Governance materials such as the declaration, bylaws, articles, meeting minutes and board information may also be requested.
TuCielo’s association financing process provides additional context on what associations can expect when presenting a financing request.
4. Define any new project scope before setting the loan amount
If the association is refinancing to fund additional work, the board should avoid choosing a loan amount before it understands the project.
Use current engineering information, contractor proposals and other relevant documentation to establish a defensible scope and budget.
If a $1 million request addresses only one part of a much larger documented repair requirement, the association could close the refinance and immediately face another funding gap.
5. Compare proposals using the same assumptions
Boards should place competing proposals side by side.
Compare:
- Principal amount financed
- Existing debt being paid off
- New money available for work
- Interest rate and whether it is fixed or variable
- Loan term
- Amortization schedule
- Estimated periodic debt service
- Closing and lender costs
- Prepayment provisions
- Required accounts or reserves
- Collateral or pledged association revenues
- Financial covenants
- Conditions for future borrowing
If one proposal finances fees while another requires them to be paid in cash, adjust the comparison so the board is looking at equivalent costs.
6. Model the effect on the association and owners
The association is the borrower, but debt service ultimately has to fit within the community’s financial plan.
The board should model the replacement loan alongside normal operating assessments, reserve funding, active special assessments, insurance costs and reasonably known capital needs.
Owners need to understand what the refinancing means in practical terms. A lower payment this year can still create a longer obligation.
7. Complete legal approval and closing review
Before final approval, association counsel should confirm borrowing authority, voting or meeting requirements, resolutions, notices and consistency with the governing documents.
The association’s accountant or financial adviser can help verify the budget and debt-service assumptions.
Only after those pieces align should the board treat the proposed refinance as a complete financing plan rather than an indicative quote.
How a refinance can fund new repairs or consolidate HOA debt
One of the more useful applications of association refinancing is combining an existing balance with a new capital requirement.
Consider a hypothetical Florida condominium with 120 units.
The association already has an outstanding loan used for an earlier building project. An updated engineering review identifies additional concrete restoration, waterproofing and mechanical work that should be addressed.
The existing lender won’t increase the loan enough to cover the revised scope.
The board could evaluate three paths.
One option is to leave the first loan untouched and finance the new work separately. This preserves the existing debt terms but results in two financing obligations.
A second option is to keep the loan and levy a special assessment for the additional work. That avoids adding another financed balance but could require owners to fund a larger amount in a shorter period.
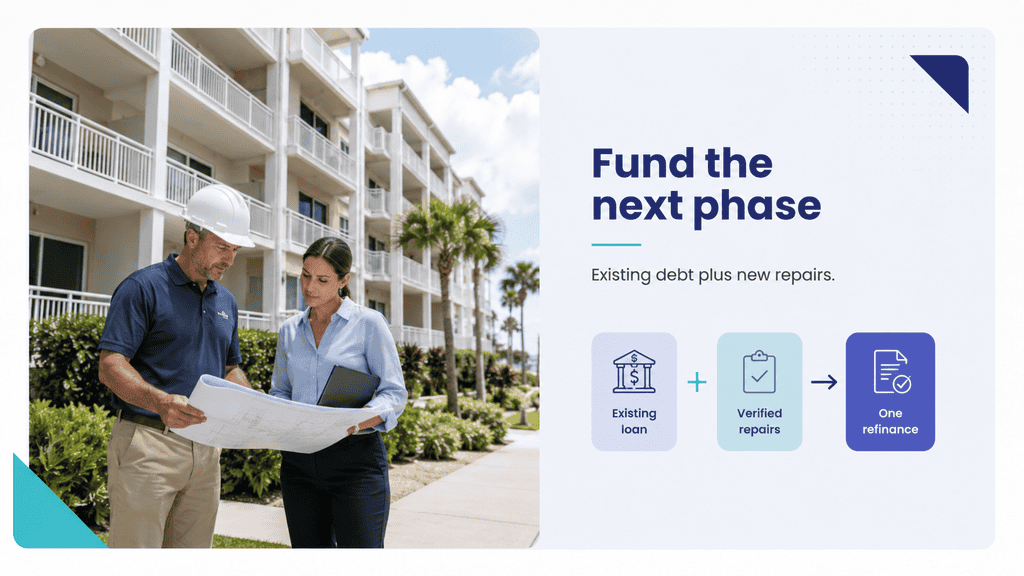
The third option is to refinance condo association loan debt into a replacement facility that pays off the original balance and provides additional funding for the verified work.
Under the third approach, the board shouldn’t compare the new loan amount with the original loan alone. It should separate the transaction into three figures:
Existing debt payoff + new project funding + financing costs = total new financing need
That simple breakdown makes it easier for directors and owners to understand why the replacement loan may be larger than the debt appearing on the prior year’s financial statements.
The same reasoning applies when a board wants to consolidate HOA debt.
Before combining obligations, identify what each debt funded, whether it can be prepaid and whether consolidation actually improves the association’s financial position. One payment may make administration easier, but convenience by itself isn’t a sufficient reason to increase borrowing costs or extend debt much longer than necessary.
Florida condominium boards also need to coordinate any new project financing with required reserve funding. Current state law specifically permits certain reserve obligations to be funded with loans or lines of credit, subject to statutory conditions, but the financing method must fit the applicable SIRS funding plan.
Questions boards should answer before approving a refinance
A refinancing decision becomes clearer when the board can answer a short set of questions in writing.
First, what does it cost to keep the existing financing until maturity? Include remaining payments and any balloon amount.
Second, what does it cost to exit the loan now? Obtain a current payoff figure and identify any prepayment costs.
Third, how much of the proposed replacement financing pays old debt and how much represents new borrowing?
Fourth, does the new term match the useful life and financial purpose of the work being financed? Stretching short-lived expenses over a very long period can shift costs to future owners long after the original benefit has been consumed.
Fifth, what happens to assessments? Model the expected debt service together with operating expenses, reserve contributions and other owner obligations.
Sixth, what restrictions will the new lender impose? Review reporting requirements, reserve requirements, collection standards, additional-debt limitations and default provisions.
Finally, has association counsel confirmed the required approval process and reviewed the financing documents?
If the answers are documented, directors have a stronger basis for explaining the decision to owners and comparing proposals on something more meaningful than the lowest advertised payment.
For Florida associations that already have a loan and want to compare a replacement structure, TuCielo’s financing eligibility form specifically asks about outstanding association debt and whether the current balance should be included in a new financing proposal. TuCielo states that existing balances may be refinanced and combined with additional financing, subject to underwriting and final terms.
FAQs
Can an HOA refinance an existing association loan?
Yes, refinancing may be possible if a lender is willing to provide replacement financing and the association meets its underwriting and approval requirements. The board should first review the current loan’s payoff amount, maturity date, prepayment terms and governing-document requirements.
Can a Florida condo association refinance a loan and borrow more money at the same time?
Potentially. A new financing structure can pay off the existing loan and include additional funding for qualified repairs or other approved purposes when the lender permits it. TuCielo states that its association financing can refinance an existing balance while adding funding for additional project scope.
Does refinancing automatically lower an HOA’s costs?
No. A lower interest rate or lower periodic payment doesn’t automatically mean the refinancing is less expensive overall. Boards should compare interest, fees, prepayment costs, repayment length and total debt service before deciding.
Can an association refinance a balloon payment?
A replacement loan may be used to pay an outstanding balance that becomes due at maturity, subject to lender approval and association authorization. Boards should begin evaluating the maturity well before the balloon becomes due so they have time to compare refinancing with other funding options.
Can refinancing be used to consolidate HOA debt?
It may be possible to combine eligible existing obligations into a single replacement financing structure. The board should obtain payoff information for each obligation and compare the total cost of consolidation with keeping the debts separate.
Does a Florida association need owner approval to refinance a loan?
The required approval depends on the type of association, governing documents, purpose of the borrowing and applicable Florida law. Certain statutory financing methods have specific voting requirements, so association counsel should confirm the process before the board approves or signs a refinance.
How can an association start evaluating a refinance with TuCielo?
Start by gathering the current loan documents, payoff information, recent financial statements, budget, delinquency report, governing documents and any project or engineering information tied to new funding. Florida boards can then use TuCielo’s eligibility review to provide details about the association, including its outstanding loan, and determine what refinancing options may be available subject to underwriting and final terms.